Americans Changing Their Budgets for How Households Are Adjusting
Groceries, housing, transportation, and subscriptions are putting pressure on monthly budgets. Here's how households are adjusting and what practical steps they consider.
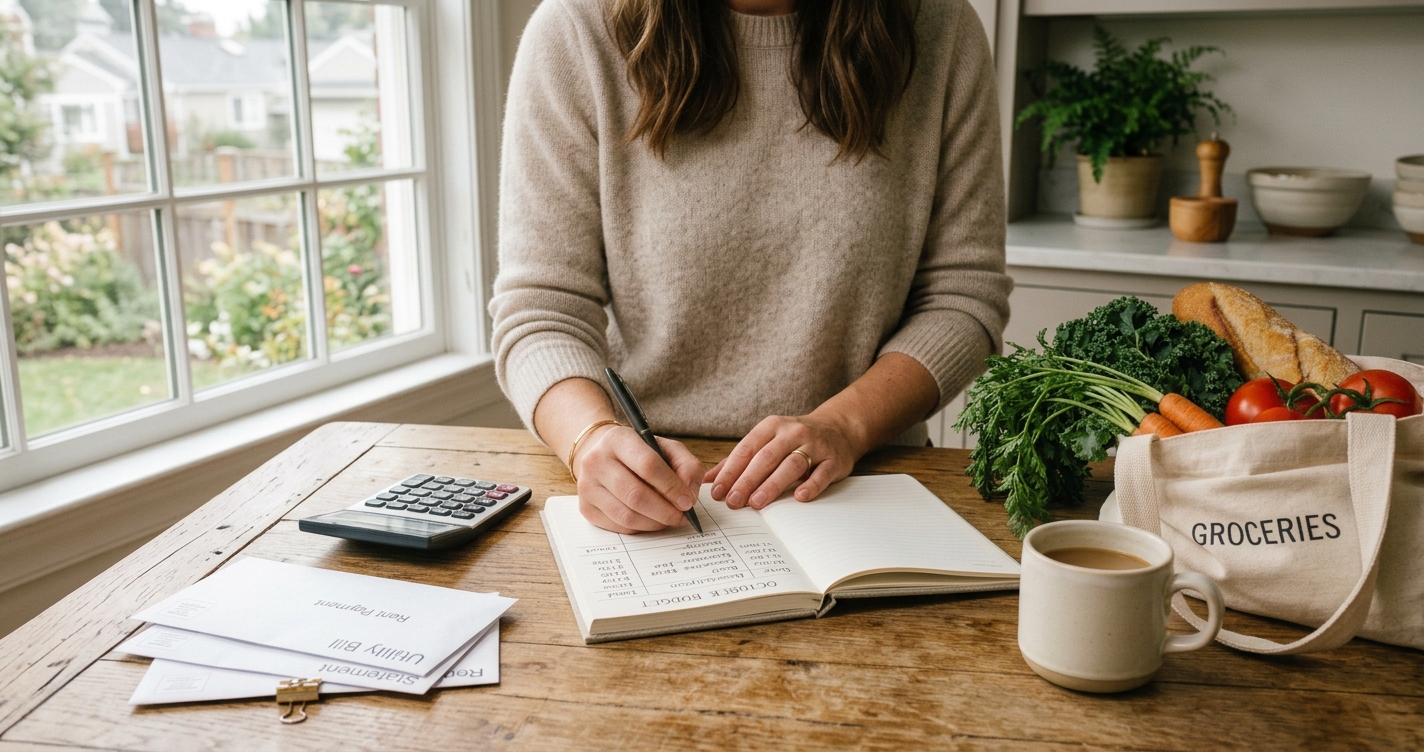
A grocery run that used to feel routine can now prompt a second look at the receipt. Across the country, many households are rethinking where their money goes each month. This article looks at how Americans are changing their budgets, which categories tend to put the most pressure on a paycheck, and what practical adjustments people consider.
Main introduction
Most people don't notice rising costs all at once. It shows up in small ways: a higher total at the checkout counter, a renewed insurance quote that's more than last year's, an electric bill that jumps during a hot summer or a cold January. Rent or a mortgage payment takes its share first, then come gas, utilities, phone service, streaming subscriptions, and the occasional dinner out. Somewhere in the middle, there's supposed to be room for savings.
When several of these costs move in the wrong direction at once, a monthly budget that once worked can start to feel tight. That's a common experience, and it doesn't mean someone has done anything wrong. This guide walks through the major spending categories and explains how households are approaching each one.
Why Household Budgets Are Getting More Attention
A budget is a plan, and plans need updating when conditions change. When prices for everyday goods and services rise faster than income, the gap between what comes in and what goes out can narrow. Even modest increases across several categories can add up, because most households pay for many things every month.
Cost of living in the US also varies a great deal by location. Rent in a large coastal city looks nothing like rent in a small Midwestern town, and heating costs in Minnesota differ from cooling costs in Arizona. That's why national averages only tell part of the story. What matters most is how the numbers look for your own household.
For the latest national price trends, the Bureau of Labor Statistics publishes the Consumer Price Index, which tracks how prices change over time for categories such as food, shelter, and energy.
Grocery Spending
Food is one of the few costs that can't be skipped, which makes grocery spending a common place to look for flexibility. Some households are changing how they shop rather than what they eat.
Approaches people commonly consider include:
- Comparing unit prices (price per ounce or pound) instead of only the sticker price
- Choosing store brands for staples like pasta, canned goods, or baking supplies
- Planning meals for the week before heading to the store
- Watching weekly promotions and digital coupons in store apps
- Cutting back on impulse buys, especially near the checkout
Meal planning gets a lot of attention because it tackles a quieter problem: food waste. A family that buys ingredients without a plan may end up throwing away produce that spoiled before anyone cooked it. That's money spent with nothing to show for it.
None of this works the same way for everyone. A household with young kids, dietary restrictions, or limited access to a nearby store will face different trade-offs than a single person living near several supermarkets.
Housing and Utility Costs
For most households, housing costs are the largest single line in the budget, whether that's rent or a mortgage payment plus property taxes and insurance. These are usually fixed expenses, meaning the amount stays roughly the same from month to month. That predictability helps with planning, but it also means there's less room to adjust quickly.
Utilities are different. Electricity, natural gas, water, and heating oil are variable expenses, and the bill can change with the seasons, the weather, and how much energy a home uses. Internet and phone plans sit somewhere in between.
Understanding the difference matters. When fixed costs take a large share of income, variable categories often become the place where households have more flexibility. Some people look at simple steps like adjusting thermostat settings, sealing drafts, or switching to more efficient light bulbs. Others check whether their utility offers budget billing, which spreads costs more evenly across the year. Availability depends on the provider, so it's worth asking directly.
Transportation Expenses
For many Americans, especially outside big cities with strong transit systems, a car is a necessity. And the car itself is only part of the cost. Fuel, insurance, registration, routine maintenance, tires, and unexpected repairs all belong in the transportation column.
Gas prices can shift from week to week, which makes this category hard to predict. Car insurance is another cost that can change at renewal, sometimes for reasons unrelated to the driver's own record. Some consumers compare quotes from multiple insurers at renewal time, or ask about discounts they may already qualify for.
Commuting habits matter too. Households with access to public transportation, carpooling, or remote work days may spend less on fuel and wear and tear. Others don't have those options, and that's a reality any budget has to account for. For everyone, setting aside a small amount monthly for maintenance can make a surprise repair less disruptive.
Eating Out and Subscriptions
Discretionary spending is where the budget tends to leak without anyone noticing. Individual purchases feel small. A coffee on the way to work, takeout after a long day, a streaming service you signed up for during one show and never canceled.
Here's a hypothetical example. Someone reviews their bank statement and finds four or five recurring charges for apps and services they rarely use. Each one seems minor, but together they take up more of the month than expected. Canceling the ones they don't use frees up room without changing anything essential.
Dining out works similarly. Some households are cooking at home more often and saving restaurant meals for occasions that matter to them. That's a preference rather than a rule, and plenty of people find that a few planned outings feel better than many unplanned ones.
Emergency Savings
Even a carefully built budget can be thrown off by a car repair, a medical bill, or a gap between jobs. An emergency fund is money set aside specifically for situations like these, so an unexpected cost doesn't have to go on a credit card.
How much someone keeps in emergency savings varies with their income, job stability, family size, and other factors. Many general financial education resources describe a cushion covering a few months of essential expenses as a common goal, though it can take time to build and any amount helps. The Consumer Financial Protection Bureau offers free educational material on building savings.
For households already stretched thin, starting small is a common approach. A modest, regular contribution is often easier to keep up than an ambitious one that gets abandoned after a month. Some people also keep an eye on stock market trends when deciding how to grow savings over time, though a basic cushion usually comes first.
Separating Needs From Wants
One of the most useful budget exercises is sorting expenses into needs and wants. It sounds simple, but the lines aren't always sharp.
Housing, basic groceries, utilities, transportation to work, health insurance, and minimum debt payments generally fall under needs. Streaming services, premium cable packages, frequent dining out, and impulse shopping usually fall under wants.
Then there's the gray area. A phone is a need, but the most expensive plan might not be. Groceries are a need, but pre-packaged convenience foods might be more of a preference. Internet is essential for many people, though the speed tier is a choice. Working through these gray areas honestly helps a household decide where flexibility exists and where it doesn't.
Small Changes That Can Help a Monthly Budget
Big overhauls are hard to sustain. Smaller adjustments are often easier to stick with, and they may help some households reduce unnecessary spending without dramatic lifestyle changes.
- Review recurring subscriptions and cancel anything that's no longer being used
- Compare prices on groceries, insurance, and phone or internet plans
- Plan grocery purchases around a list and a weekly meal outline
- Track monthly expenses using a spreadsheet, a notebook, or a budgeting app
- Set spending limits for flexible categories like dining out or entertainment
- Review insurance coverage periodically to make sure it still fits your situation
- Pause before impulse purchases, giving yourself a day before buying non-essentials
Results vary, and no single step fits every household. The goal is to find a few changes that feel realistic rather than trying to do everything at once.
Building a More Realistic Monthly Budget
A monthly budget doesn't need to be complicated. This basic process is one that many financial education resources describe:
- Identify monthly income. Use take-home pay, and if income varies, consider using a lower, conservative estimate.
- List essential expenses. Include housing, utilities, food, transportation, insurance, and minimum debt payments.
- Review recurring expenses. Look at bank and card statements for subscriptions, memberships, and automatic payments.
- Identify flexible spending. Separate categories like dining out, entertainment, and shopping.
- Set aside money for unexpected costs. Even a small amount directed toward emergency savings counts.
- Review the budget regularly. Prices, income, and life circumstances change, so a monthly check-in keeps the plan realistic.
A budget that looks perfect on paper but ignores real life tends not to last. Including a little room for irregular costs, like annual fees or holiday spending, makes the plan easier to follow.
Frequently Asked Questions
What are the biggest expenses in most household budgets?
For most U.S. households, housing is the largest expense, followed by transportation and food. Health care, insurance, and utilities also take a meaningful share. The exact mix depends on location, family size, and income. The Bureau of Labor Statistics' Consumer Expenditure Surveys break down average spending by category.
How often should I review my monthly budget?
Many people check in once a month, often when bills are due or paychecks arrive. It also helps to review after a major change, such as a new job, a move, or a large price increase in a key category.
What counts as an emergency fund expense?
Emergency savings are generally intended for unexpected and necessary costs, such as urgent car or home repairs, medical bills, or a temporary loss of income. Planned purchases and routine expenses usually belong in the regular budget instead.
Is it better to cut expenses or increase income?
Both approaches can help, and they aren't mutually exclusive. Adjusting spending is often the quicker step because it's within your direct control. Increasing income, through a raise, additional work, or new skills, usually takes longer and depends on circumstances. This is general information, not personal advice, and a nonprofit credit counselor can help with individual situations.
Are budgeting apps worth using?
Some people find that apps make it easier to see spending patterns, while others prefer a spreadsheet or pen and paper. The best tool is usually the one you'll actually keep using. Check any app's privacy policy and fees before linking bank accounts.
Conclusion
Americans changing their budgets isn't a sign of failure. It's a practical response to real pressure on household expenses. The categories that often matter most are the ones that recur every month: housing, groceries, transportation, and utilities. Looking at those honestly, separating needs from wants, and building in room for surprises can make a monthly budget feel more manageable.
You don't have to change everything at once. Many households start with one or two categories, such as subscriptions or grocery planning, and adjust from there. Checking in on your numbers regularly helps you notice changes early, and that alone can make financial decisions feel more manageable.
Written by
EmmaYou might also like
How to Find Affordable Health Insurance in 2027
Confused by deductibles and plan levels? This beginner’s guide explains 2027 health insurance in plain English.
No-GMAT MBA Programs in the US for Finance Careers
Looking for a no-GMAT MBA for a finance career? See how GMAT waivers work, who qualifies, 8 US programs to explore, and how to apply step by step.
Small Business Financing Options: A Guide to Choosing the Right One
Not sure which kind of funding fits your business? This guide explains every major option, from bank loans to grants, and walks you through a practical way to choose.
How Financial Services Are Changing in the US in 2026
Banking apps, AI, instant payments, and embedded finance are changing how Americans manage money. Explore the financial services trends 2026 and learn simple ways to stay safe and save smarter.
 Trending
US Stock Market Outlook Sept 2026: Fed, Inflation & Oil
Inflation, an oil price shock from Middle East conflict, and a critical Fed decision are colliding to shake U.S. markets.
Fed Rate Decision September 16 Turns Into a Total Toss-Up
Discover why the Fed's September 16 rate decision has become a coin flip, as oil-driven inflation, mixed jobs data and Chair Kevin Warsh's hawkish tone keep pulling the odds between a hike and a hold.
Comments (0)
Be the first to comment.